Katowice’s Primary Residential Market at the End of 2026: More Than 6,000 Apartments Available. Which Developments Lead the Market, and What Are the Prices?
More than 6,000 apartments across 82 developments, with a median asking price of PLN 12,610 per square metre. Explore Katowice’s leading projects, district supply and price differences.
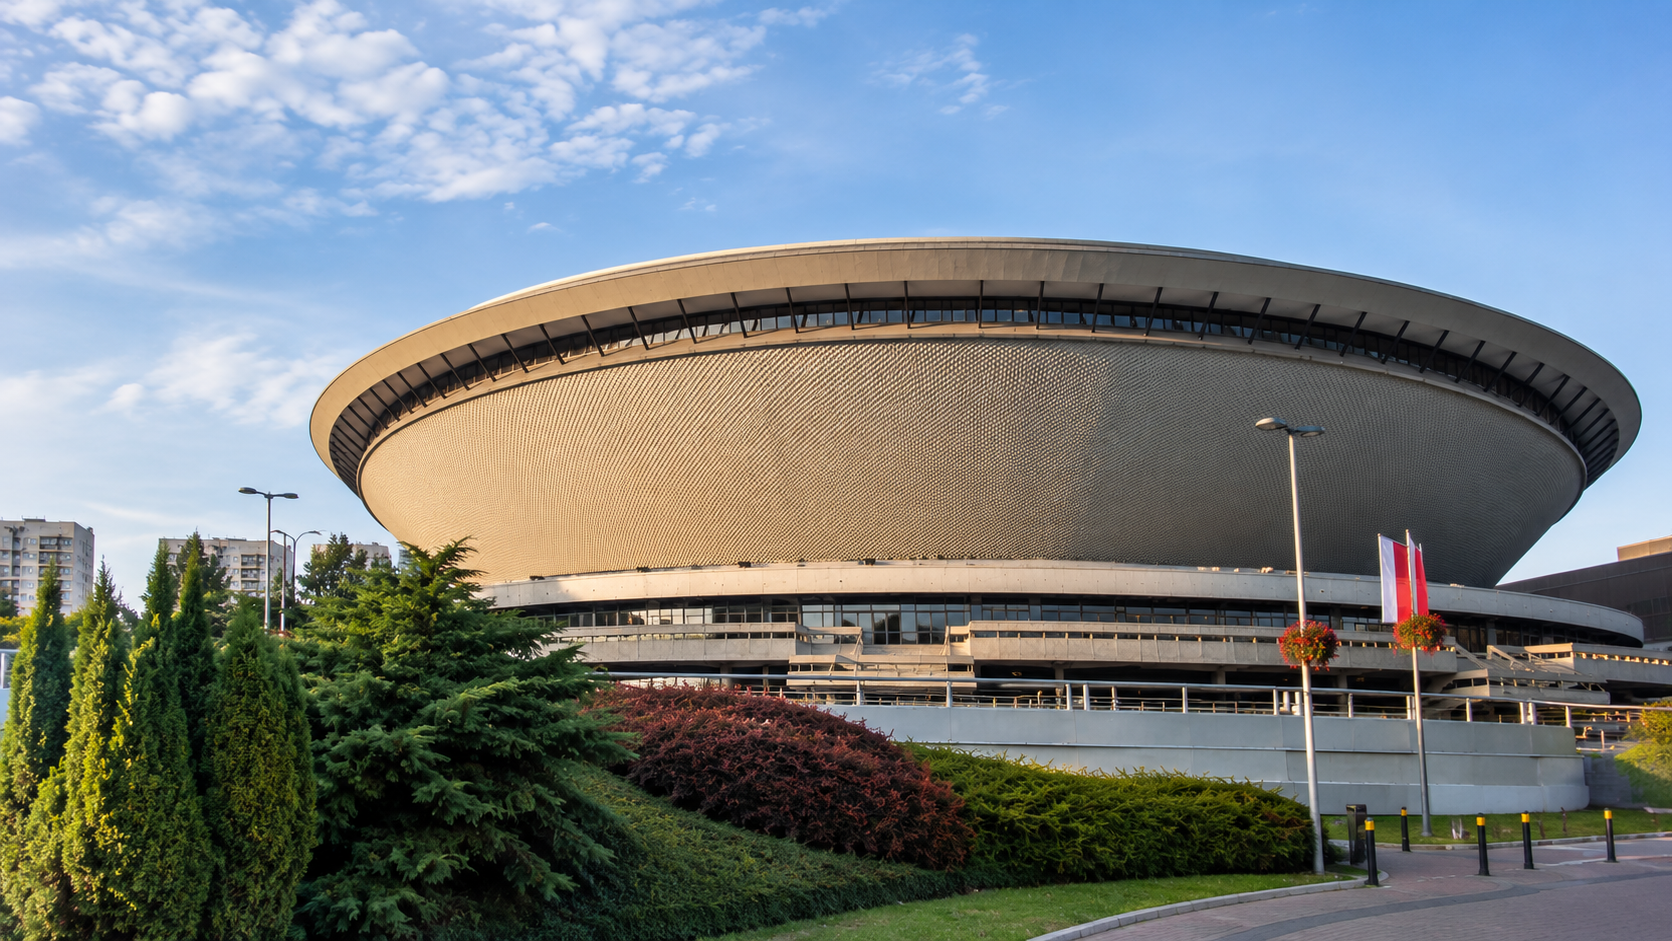
Katowice is approaching the end of 2026 with a substantial supply of newly built apartments, a high concentration of available units in several districts, and significant price differences between individual residential developments. As of early November, the monitored market comprised 82 developments offering 6,106 apartments, with a median asking price of PLN 12,610 per square metre. The largest available inventories were recorded in projects developed by ATAL, Trust Investment and other major market participants. However, a closer examination of individual schemes reveals a highly segmented market, with differences in median asking prices exceeding PLN 4,000 per square metre between selected developments.
More Than 6,000 Apartments on the Market
Katowice remains one of southern Poland’s important primary residential markets. New residential development is concentrated both in central districts and in locations offering sufficient land and planning capacity for larger, multi-phase projects.
According to Mieszkaniometr data dated 7 November 2026, the monitored primary market in Katowice comprised 82 residential developments, with 6,106 apartments listed as available for sale. The citywide median asking price stood at PLN 12,610 per square metre.
The scale of available supply is relevant to developers, investors and prospective buyers alike. It illustrates the competitive environment but does not, in itself, establish whether the market is experiencing oversupply.
A reliable assessment of the supply-demand balance would require verified information on monthly apartment sales, the pace at which new development phases enter the market, and the absorption of existing inventory.
It is also important to distinguish apartments offered in projects at an early stage of construction from completed units available for immediate occupation. These represent different products from both a buyer’s and a developer’s perspective.
The Katowice market is characterised by a notable concentration of available inventory within large residential schemes. Some projects have several hundred apartments listed for sale, while smaller developments offer only a few dozen units.
Consequently, the commercial strategies and construction schedules of the largest developers have a considerable influence on the overall market.
The Largest Available Inventories: ATAL, Trust Investment and Multi-Phase Developments
A project-level snapshot dated 1 November 2026 shows that some of the largest available apartment inventories were recorded in developments undertaken by ATAL.
At the Szybowcowa development, 465 apartments were listed as available, with a median asking price of PLN 10,872 per square metre.
Another major ATAL development, Olimpijska, had 420 apartments available, with a median asking price of PLN 13,768 per square metre.
The difference between the median asking prices of these two projects amounted to PLN 2,896 per square metre, or approximately 26.6% relative to Szybowcowa.
This illustrates how developments undertaken by the same company can operate in substantially different price segments.
Other significant inventories were recorded at Nowa Gwiazda, NOHO Nadgórników, ATAL Korfantego and O27 Apartamenty Opolska.
Nowa Gwiazda, developed by Trust Investment, had 293 apartments listed for sale, with a median asking price of PLN 14,000 per square metre.
NOHO Nadgórników recorded 274 available apartments and a median price of PLN 13,327 per square metre.
ATAL Korfantego had 270 apartments available, with a median asking price of PLN 12,353 per square metre.
Meanwhile, O27 Apartamenty Opolska, another Trust Investment development, offered 257 apartments at a median asking price of PLN 14,850 per square metre.
Together, these six projects represented 1,979 apartments listed as available in the 1 November snapshot.
Their scale demonstrates the importance of major developments in shaping Katowice’s residential supply.
However, the interpretation of project-level data requires careful consideration of how individual buildings and development phases are grouped.
A project appearing as a single entry in a property database does not necessarily correspond to one construction phase or one legally defined development.
For this reason, reported apartment availability should be treated as a snapshot of monitored listings rather than a definitive inventory of all unsold units within an entire development.
ATAL: A Significant Presence Across Several Market Segments
ATAL stands out in the analysed dataset through its presence in several large residential developments.
In addition to Szybowcowa and Olimpijska, the developer maintained a substantial offer along Aleja Korfantego.
The development identified as ATAL Korfantego comprised 270 apartments listed as available, with a median asking price of PLN 12,353 per square metre.
The database also included separate entries relating to other developments or phases along the same avenue.
These should not be aggregated without confirming that they represent distinct buildings and non-overlapping inventories.
Nevertheless, the price differences between ATAL’s principal projects are significant.
Szybowcowa, with a median price of PLN 10,872 per square metre, was positioned below the citywide median. Olimpijska, at PLN 13,768 per square metre, was positioned above it.
For prospective buyers, this creates opportunities to compare apartments offered by the same developer across different locations and price categories.
For competing developers, ATAL’s pricing strategies may influence the positioning of nearby projects, particularly where apartment sizes, specifications and target customer groups overlap.
However, the number of available apartments alone does not establish which ATAL development is achieving the strongest sales performance.
Such an assessment would require comparable information on contracted sales, reservations and the total number of apartments released for sale in each development phase.
Trust Investment: A Strong Presence in Higher Price Segments
Trust Investment is another important participant in Katowice’s primary residential market.
Two of its major projects in the analysed dataset are Nowa Gwiazda and O27 Apartamenty Opolska.
Nowa Gwiazda had 293 apartments available, with a median asking price of PLN 14,000 per square metre.
O27 Apartamenty Opolska recorded 257 available units, with a median asking price of PLN 14,850 per square metre.
Both developments were positioned above the citywide median asking price.
In the case of O27, the difference relative to the citywide median recorded in early November amounted to PLN 2,240 per square metre.
For an illustrative 50-square-metre apartment, this would translate into a price difference of approximately PLN 112,000.
The comparison is indicative rather than like-for-like, as apartments across developments may differ in size, specification, layout and other characteristics.
Nevertheless, the figures demonstrate Trust Investment’s substantial presence in the higher-priced segments of Katowice’s residential market.
The database also included Koronki Apartamenty Korfantego, associated with Trust Investment, with 131 apartments available and a median asking price of PLN 11,500 per square metre.
This shows that the developer’s monitored portfolio also spans different price categories.
Bogucice: The Largest Concentration of Available Apartments
Bogucice had the highest number of apartments listed as available among Katowice’s districts.
According to the 7 November data, the district contained 1,058 available apartments across five monitored developments, with a median asking price of PLN 13,500 per square metre.
Bogucice therefore accounted for approximately 17.3% of the city’s monitored available inventory.
Major contributors included developments located along Olimpijska, Nadgórników and Góreckiego streets.
ATAL Olimpijska had 420 apartments available, with a median asking price of PLN 13,768 per square metre.
NOHO Nadgórników offered 274 apartments, with a median of PLN 13,327 per square metre.
Pierwsza Dzielnica, developed by TDJ Estate, recorded 156 available apartments at a median asking price of PLN 14,450 per square metre.
Additional developments were monitored along Katowicka and Kopalniana streets.
Bogucice is therefore one of the principal areas of competition among residential developers in Katowice.
However, the differences between individual projects demonstrate that the district does not represent a uniform product or price category.
Buyers considering apartments of similar sizes and within comparable total budgets may be able to evaluate several developments located relatively close to one another.
For developers, this increases the importance of product differentiation.
Competitive positioning depends not only on the asking price but also on architectural quality, apartment layouts, communal facilities, parking provision, the immediate surroundings and construction schedules.
At the same time, a large number of available apartments in Bogucice does not automatically indicate weak sales performance.
It may simply reflect the scale of developments currently being marketed and the number of apartments released for sale.
Without verified sales absorption data, there is insufficient evidence to classify the district as oversupplied.
Paderewskiego-Muchowiec: Substantial Supply and Diverse Pricing
Paderewskiego-Muchowiec ranked second in terms of monitored available apartment inventory.
At the beginning of November, the district had 663 apartments listed for sale across six developments, with a median asking price of PLN 12,369 per square metre.
One of its largest projects was Szybowcowa, which had 465 available apartments in the 1 November snapshot.
Another significant development was located along Przemysłowa Street and associated with Cavatina SPV 32.
The project had 175 apartments available, with a median asking price of PLN 13,500 per square metre.
The difference between the median asking prices of Szybowcowa and the Przemysłowa development amounted to PLN 2,628 per square metre.
For an illustrative 50-square-metre apartment, this would represent a difference of approximately PLN 131,000.
The calculation does not imply that apartments in the two developments are directly comparable. It does, however, illustrate the significance of individual project characteristics and micro-location.
For buyers, the availability of competing projects creates opportunities to compare apartments with similar floor areas.
For developers, it highlights the need to justify pricing through the actual characteristics of a development rather than relying solely on the general attractiveness of a district.
Wełnowiec-Józefowiec: Multiple Projects Across a Broad Price Range
Wełnowiec-Józefowiec is another important area of residential development activity.
According to the 7 November snapshot, the district contained 618 apartments available for sale across eight monitored developments.
The median asking price stood at PLN 11,750 per square metre, below the citywide median.
One of the largest projects was ATAL Korfantego, with 270 available apartments and a median price of PLN 12,353 per square metre.
Koronki Apartamenty Korfantego recorded 131 available apartments, with a median asking price of PLN 11,500 per square metre.
Another project was Murapol’s development along Konduktorska Street, with 75 available apartments and a median asking price of PLN 13,750 per square metre.
These differences demonstrate why a district-level median cannot fully represent the pricing structure of individual developments.
When evaluating a particular apartment, buyers should consider not only prices in neighbouring schemes but also specifications, completion dates, available layouts and the overall purchase cost.
Accurate identification of individual developments and phases is particularly important where several projects are located along the same major roads.
Apartment inventories should not be combined unless it has been established that the underlying listings are distinct.
Śródmieście: Higher Prices and Competition Between Central Developments
Śródmieście remains one of Katowice’s more expensive primary residential locations.
At the beginning of November, the district had 536 apartments available across seven monitored developments, with a median asking price of PLN 13,877 per square metre.
One of the largest projects was O27 Apartamenty Opolska, with 257 apartments available in the 1 November snapshot and a median asking price of PLN 14,850 per square metre.
Other developments were recorded along Kozielska Street and at Barbary 19.
The Antrans Invest development on Kozielska Street comprised 127 apartments listed as available, with a median asking price of PLN 12,098 per square metre.
Barbary 19 had 74 available apartments, with a median price of PLN 13,850 per square metre.
Kozielska Park offered 68 apartments, with a median asking price of PLN 12,189 per square metre.
In central locations, pricing differences may reflect building design, communal facilities, surrounding urban infrastructure, transport accessibility and apartment sizes.
Central residential projects may also appeal to different groups of purchasers.
Some buyers seek apartments for owner-occupation, while others consider residential property as an investment or prioritise larger apartments in a central location.
However, without project-level sales information, it would be inappropriate to conclude which buyer group dominates demand in any particular development.
Zawodzie: Major Projects in a Relatively High Price Segment
In Zawodzie, 472 apartments were listed as available across two monitored developments at the beginning of November.
The district’s median asking price was PLN 13,600 per square metre.
One of its principal projects was Nowa Gwiazda, with 293 apartments available and a median asking price of PLN 14,000 per square metre.
The second major entry was a Dasta Investment project along Paderewskiego Street.
This development had 179 apartments available, with a median asking price of PLN 13,300 per square metre.
Together, these two projects accounted for the district’s monitored available inventory in the analysed snapshot.
This illustrates a market structure in which a substantial share of supply is concentrated within a small number of large developments.
Consequently, competitive analysis should extend beyond asking prices to include construction schedules, apartment mix and target customer groups.
Where supply is concentrated in only a few projects, the commercial decisions of individual developers can have a considerable influence on local market conditions.
Southern Katowice: An Alternative to Central Locations
Piotrowice-Ochojec, Kostuchna, Zarzecze and other southern districts form a distinct part of Katowice’s primary residential market.
At the beginning of November, Piotrowice-Ochojec had 434 apartments available, with a median asking price of PLN 12,350 per square metre.
Among its significant developments was Murapol’s project on Rzepakowa Street, with 187 apartments available and a median asking price of PLN 14,950 per square metre.
The database also included a development on Waltera-Jankego Street associated with Recap SPV 22, comprising 160 available apartments at a median asking price of PLN 11,850 per square metre.
The difference between the two project medians amounted to PLN 3,100 per square metre.
In Kostuchna, 159 apartments were listed as available, with a district median of PLN 11,250 per square metre.
One of the projects was a TDJ Estate development on Hierowskiego Street, with 111 available apartments and a median asking price of PLN 11,450 per square metre.
In Zarzecze, 63 apartments were available, with a median asking price of PLN 10,527 per square metre.
Ostoja Zarzecze was one of the monitored projects, with 56 available apartments and a median price corresponding to the district-level figure.
In southern locations, the total purchase price and functional characteristics of an apartment may be particularly relevant to buyers comparing different residential options.
However, it would be incorrect to assume that all developments outside the city centre are less expensive.
Murapol’s Rzepakowa project demonstrates that southern Katowice also contains developments with median asking prices substantially above the citywide level.
Project-Level Prices Reveal the Market’s Segmentation
Comparing individual developments provides a more detailed understanding of Katowice’s pricing structure than the citywide median alone.
In the 1 November snapshot, ATAL Szybowcowa had a median asking price of PLN 10,872 per square metre.
The corresponding figures were PLN 13,768 for ATAL Olimpijska, PLN 14,000 for Nowa Gwiazda and PLN 14,850 for O27 Apartamenty Opolska.
Osiedle Józefowska recorded a median price of PLN 11,600 per square metre, with 202 apartments listed as available.
Pierwsza Dzielnica had a median of PLN 14,450 per square metre, while Koronki Apartamenty Korfantego stood at PLN 11,500 per square metre.
The difference between selected developments exceeded PLN 4,000 per square metre.
For a hypothetical 50-square-metre apartment, this would translate into a total price difference exceeding PLN 200,000.
This does not establish that one development is more expensive than another on a like-for-like basis.
Project medians may reflect different apartment sizes, layouts, floor levels, specifications and orientations.
Nevertheless, the comparison identifies the price segments in which individual developments operate.
For developers, this information is relevant when positioning projects against competing schemes.
For buyers, it provides a starting point for evaluating apartments with comparable characteristics.
October 2026: Limited Changes in Developers’ Asking Prices
Data for October 2026 indicates relatively modest changes in asking prices across Katowice’s primary residential market.
At the end of the month, the monitored database contained 5,885 available apartments, with a median asking price of PLN 12,548 per square metre.
The median declined by 0.4% compared with September.
However, the average price change for the same apartments appearing in the database at the end of both months was +0.2%.
The distinction between these measures is important.
A change in the median asking price of the entire available inventory can result from new apartments entering the market, units leaving the offer or changes in the composition of available developments.
It does not necessarily indicate widespread revisions to developers’ price lists.
By contrast, changes in the asking prices of the same apartments provide a more direct indication of developers’ current pricing decisions.
In October, price reductions affected 3.5% of the monitored apartment inventory in Katowice.
The data therefore does not indicate widespread price cutting.
Nor does it suggest that prices remained unchanged in every development.
Pricing strategies may vary between projects and even between individual apartments within the same development.
In large residential schemes, the composition of the remaining available inventory can be particularly important.
Apartments with less conventional layouts, larger floor areas or specific positions within a building may require different commercial strategies from units attracting stronger buyer interest.
Without detailed sales data, however, it is not possible to identify which Katowice developments are experiencing the greatest sales pressure.
Available Apartments Are Not the Same as Total Unsold Inventory
Accurate interpretation of apartment status is essential when analysing the primary residential market.
The number of apartments listed as available in a property database does not necessarily correspond to the total number of unsold units across an entire development.
Many developers deliver projects in phases, with individual buildings released for sale at different times.
Some apartments may be reserved, others may not yet have been launched, and certain units may be temporarily removed from public price lists.
Consequently, it would be inappropriate to calculate apartment sales simply by subtracting available listings from the total number of apartments planned within a development.
Such an approach could produce substantial errors, particularly in large multi-phase schemes.
Similarly, a reduction in available listings between two snapshots does not automatically establish that the corresponding apartments have been sold.
Changes may reflect reservations, adjustments to published inventories, corrections to the underlying data or other factors.
A reliable assessment of sales performance requires verified apartment statuses covering comparable development phases and reporting periods.
For this reason, the present analysis focuses on documented available inventory and asking prices without attributing unverified sales figures to individual developers.
What Does the Available Supply Mean for Competition in 2027?
The scale of available residential inventory in Katowice makes competition between individual developments an important consideration for the coming quarters.
The largest projects have several hundred apartments listed for sale, while supply in some districts is concentrated within a relatively small number of major schemes.
For developers, this increases the importance of managing apartment mix, pricing and the timing of new releases.
Construction and sales schedules also matter.
Launching a large number of apartments within a relatively short period may intensify local competition, particularly where projects offer similar floor areas and price ranges.
Conversely, phased sales launches can allow developers to adjust available supply to observed market demand.
For buyers, the breadth of available inventory creates opportunities to compare competing developments, although it does not establish the future direction of prices.
A key factor will be the pace at which available apartments are contracted and the rate at which developers introduce additional units.
Without verified current sales data, it would be premature to forecast the scale of potential price reductions or identify individual developments at risk of slower absorption.
What can be established is that Katowice remains a highly differentiated market in terms of location, project size and pricing.
Katowice: A Market Defined by Large Developments and Diverse Price Levels
Katowice is approaching the end of 2026 with more than 6,000 apartments listed as available and 82 monitored residential developments.
The largest inventories are concentrated in projects undertaken by ATAL, Trust Investment and other significant developers operating in the city.
Bogucice, Paderewskiego-Muchowiec, Wełnowiec-Józefowiec and Śródmieście collectively account for almost half of the monitored available inventory.
At the same time, asking prices vary considerably between individual developments.
In major projects, median asking prices range from below PLN 11,000 per square metre to approximately PLN 14,000–15,000 per square metre.
The citywide median of PLN 12,610 per square metre is therefore insufficient to assess the competitive position or value proposition of any particular development.
October data indicates limited changes in asking prices and provides no evidence of widespread price reductions.
However, the most important factor for the coming quarters will be the market’s actual capacity to absorb available inventory.
For developers, the key considerations remain apartment mix, competitive pricing and the timing of subsequent development phases. For buyers, the extensive range of projects offers opportunities to compare locations, specifications and total acquisition costs.
Katowice remains a market in which the commercial positioning of individual developments depends on their specific characteristics rather than the citywide price level alone.
---
Methodology and Sources
This analysis covers exclusively the primary residential market in Katowice, Poland.
Citywide and district-level figures are based on a market snapshot dated 7 November 2026. Detailed project-level figures are based on Mieszkaniometr data recorded on 1 November 2026.
October pricing indicators are drawn from Mieszkaniometr’s monthly market report.
The number of available apartments refers to units included in the monitored listings. It should not be interpreted as an independently verified count of all unsold apartments within an entire development.
The article does not present project-level sales volumes, sales ratios or rankings of sales absorption because sufficiently verified and comparable data was not available for the relevant development phases.
Sources: Mieszkaniometr, publicly available developers’ price lists, and Poland’s public data portal.