Warsaw’s Primary Residential Market at the End of 2026: More Than 16,600 Apartments Available. Which Districts and Developments Lead the Market?
More than 16,600 apartments across 515 developments, with a median asking price of PLN 17,250 per square metre. Explore Warsaw’s leading projects, district supply and price differences.
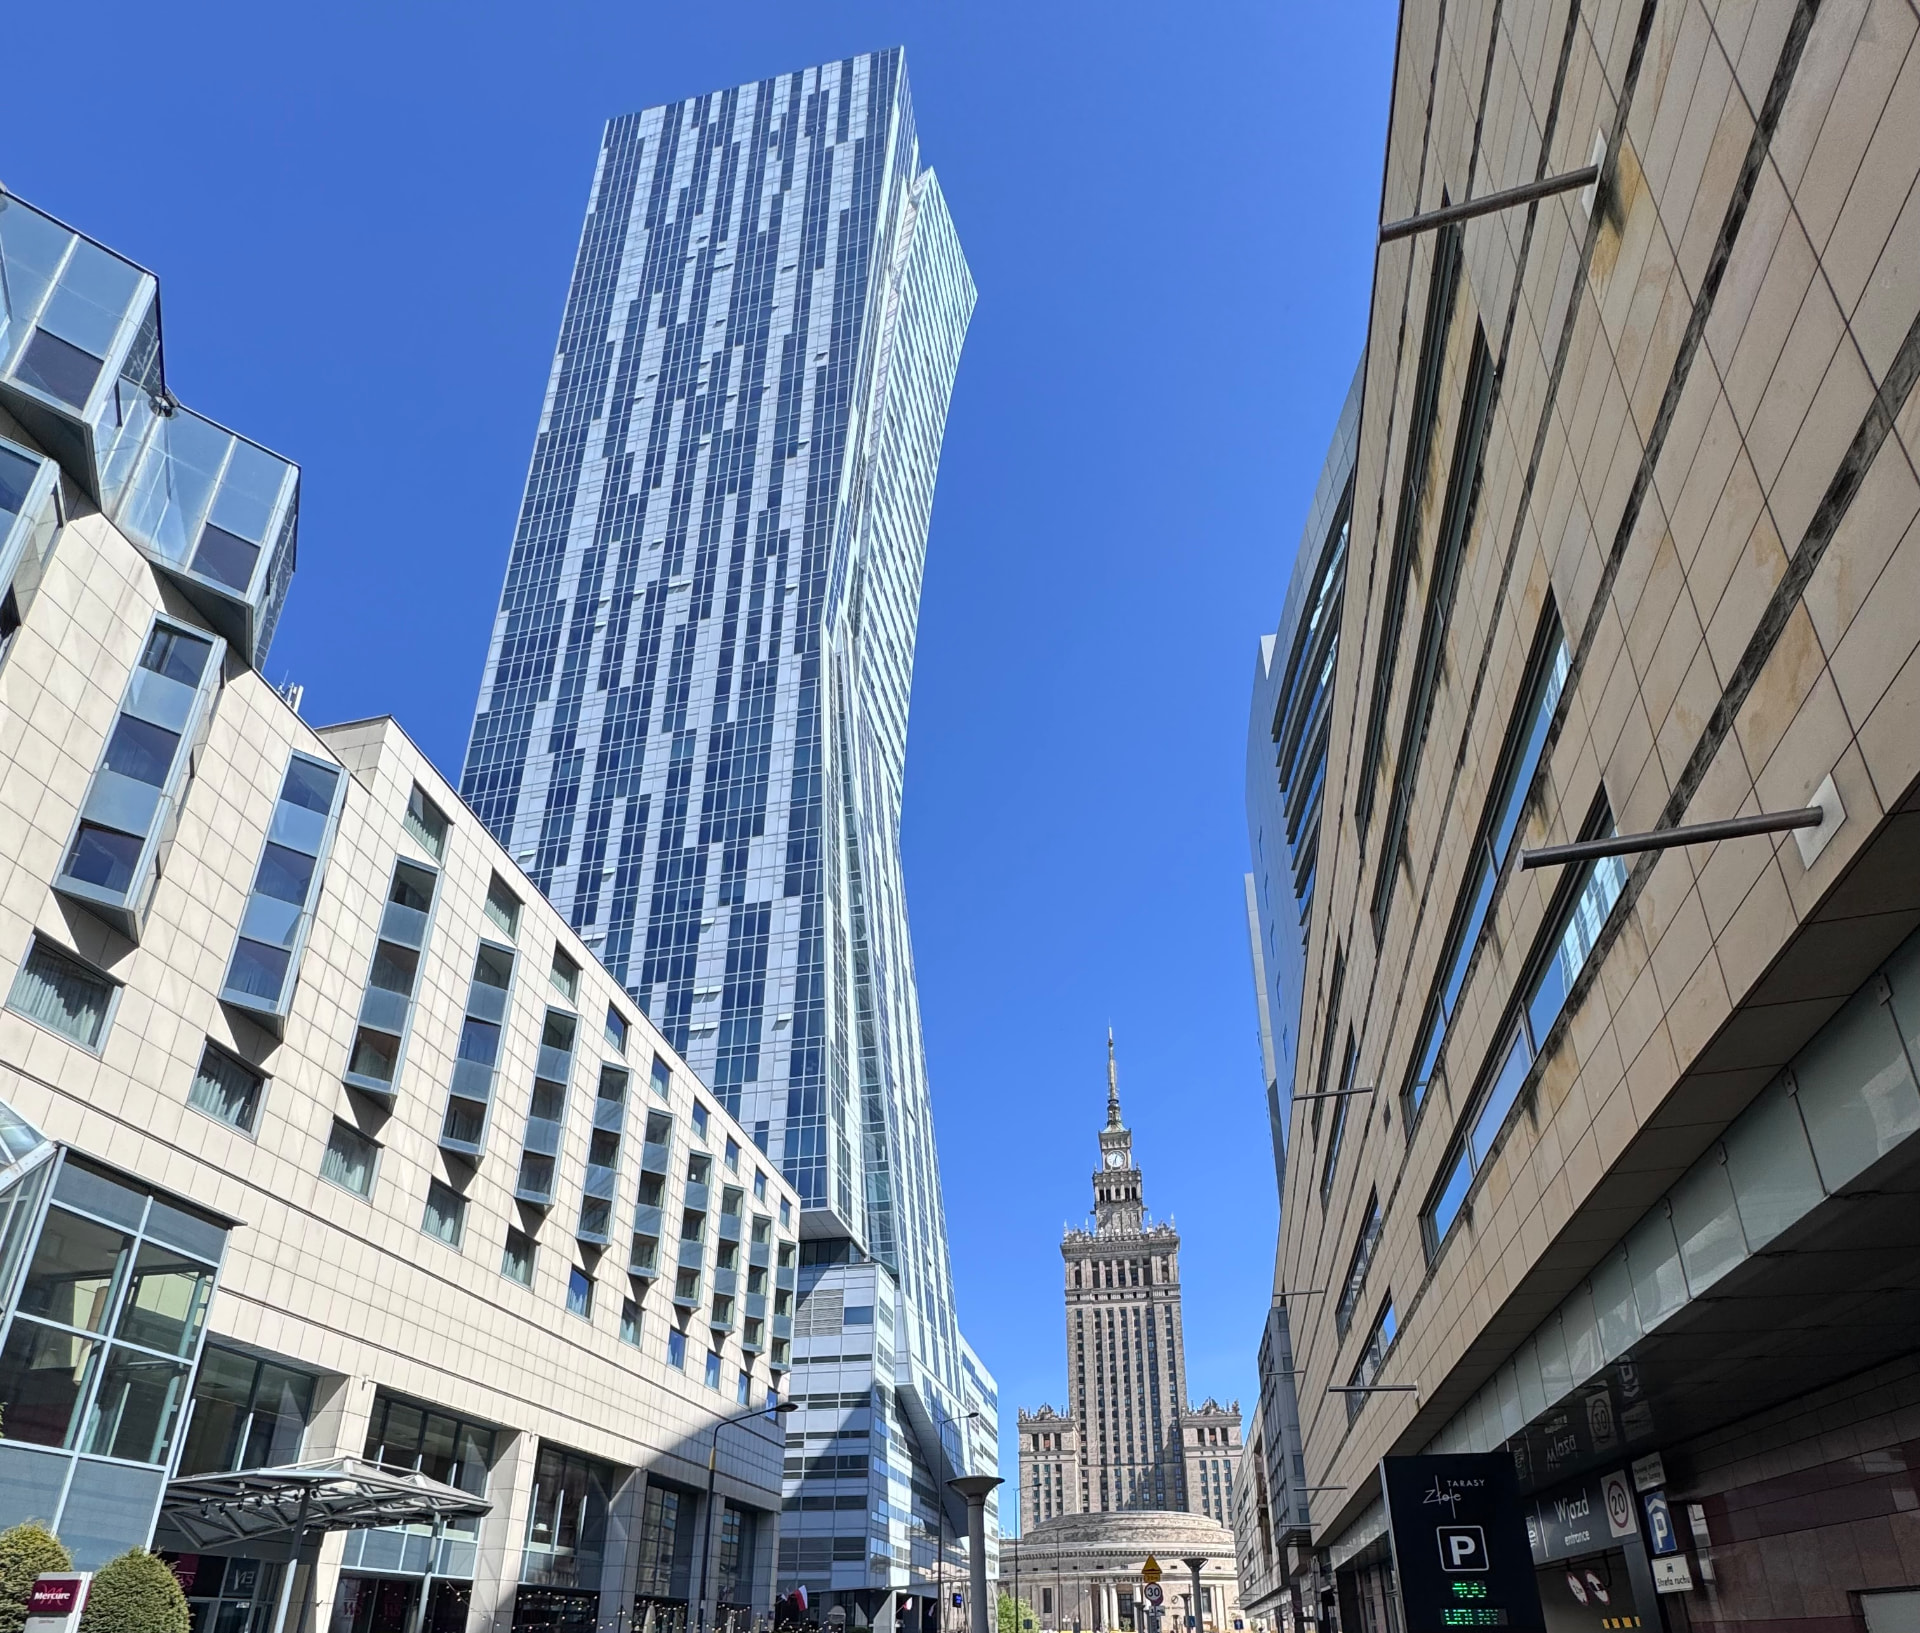
Warsaw enters the final months of 2026 with one of Poland’s largest and most diversified primary residential markets. As of 7 November, the monitored market comprised 515 residential developments offering 16,618 apartments, with a median asking price of PLN 17,250 per square metre. The capital’s residential supply is concentrated in several major districts, particularly Białołęka, Praga-Północ, Mokotów and Wola. However, the market is far from homogeneous: median asking prices range from approximately PLN 13,700–14,000 per square metre in some outer districts to more than PLN 34,000 in Śródmieście and PLN 37,000 in Wola. An examination of individual developments reveals the scale of this segmentation and the different commercial strategies operating across Warsaw’s residential market.
Warsaw’s Primary Market: More Than 16,600 Apartments Available
Warsaw remains Poland’s most extensive and geographically diverse market for newly developed residential property.
According to Mieszkaniometr, 515 residential developments were monitored across the capital on 7 November 2026. Together, they accounted for 16,618 apartments listed as available for sale.
The median asking price stood at PLN 17,250 per square metre.
These figures illustrate both the scale of Warsaw’s residential development activity and the importance of understanding the market at district and project level.
Unlike smaller regional markets, Warsaw contains several distinct residential submarkets operating within the same administrative boundaries.
A development in Białołęka may compete primarily on total purchase price, apartment functionality and access to transport infrastructure. A project in central Wola may be positioned around location, architectural quality, specification and proximity to employment centres.
Consequently, a single citywide price indicator cannot adequately describe the capital’s residential market.
The monitored inventory also represents apartments currently offered for sale rather than the total number of homes planned or constructed across all developments.
This distinction is particularly important in Warsaw, where large multi-phase projects coexist with smaller infill developments and high-value apartment schemes.
The available supply does not, by itself, establish the pace of sales or the presence of oversupply. Those conclusions would require comparable information on contracted transactions and new apartment releases.
The Largest Residential Inventories in Warsaw
The project-level data demonstrates the significance of several major developments in shaping Warsaw’s available residential supply.
Among the largest entries in the 7 November Mieszkaniometr snapshot was a development associated with Mennica Polska on Jagiellońska Street in Praga-Północ.
The monitored inventory comprised 675 apartments, with a median asking price of PLN 17,900 per square metre.
Another substantial project was located on Grzybowska Street in Wola and associated in the database with Recap SPV 8.
It contained 396 apartments listed as available, with a median asking price of PLN 38,600 per square metre.
HI Poborzańska III, located in the Warszawski Świt area of Targówek, recorded 386 available apartments and a median asking price of PLN 16,281 per square metre.
A development associated with Marvipol on Aleje Jerozolimskie in Ursus had 358 apartments available, with a median asking price of PLN 27,960 per square metre.
Home Factory in Praga-Północ had approximately 300 apartments listed as available, with a median asking price of PLN 16,200 per square metre.
NOHO Warszawa on Karolkowa Street in Wola recorded 277 available apartments, with a median asking price of PLN 50,091 per square metre.
UDI TAU, located on Herbu Oksza Street in Ursus, had 253 apartments available, with a median asking price of PLN 16,400 per square metre.
The differences between these developments are considerable.
The median asking price at NOHO Warszawa was more than three times that recorded at Home Factory.
This does not imply a like-for-like comparison between equivalent apartments. Instead, it demonstrates the existence of distinct residential product segments within the same city.
The project figures are snapshots of monitored listings. Where a development consists of several phases or is marketed through different legal entities, the reported inventory should not automatically be interpreted as the total number of unsold apartments across the entire scheme.
Białołęka: Warsaw’s Largest Concentration of Available Apartments
Białołęka had the highest number of apartments listed as available among Warsaw’s districts.
On 7 November, the district contained 2,314 apartments across 78 monitored developments.
Its median asking price stood at PLN 13,882 per square metre, approximately 19.5% below the citywide median.
Białołęka accounted for nearly 14% of the capital’s monitored apartment inventory.
The district’s market position is shaped by its substantial geographical area, relatively extensive development opportunities and range of residential projects.
The monitored developments include schemes along Geometryczna, Płochocińska, Ostródzka and other streets serving different parts of the district.
In the late-October project snapshot, a Budomatex development on Geometryczna Street had 191 apartments available, with a median asking price of PLN 13,000 per square metre.
ATAL’s development on Płochocińska Street recorded 146 apartments, with a median asking price of PLN 12,636 per square metre.
Other monitored developments included PHN Młoda Białołęka 3, with 170 apartments and a median of PLN 13,000 per square metre, and WERANDOVA, with 117 apartments and a median of PLN 11,700 per square metre.
The district therefore contains substantial inventory below the Warsaw median.
For purchasers, the relevant comparison is not only the price per square metre but also the total acquisition cost, transport accessibility, parking provision, apartment layout and local infrastructure.
For developers, Białołęka represents a competitive market in which multiple projects can appeal to similar groups of buyers.
However, the number of available apartments should not be treated as evidence of weak demand.
The district’s large inventory may reflect the scale of development activity and the number of apartments released for sale.
Without verified sales absorption data, a definitive assessment of supply-demand balance would be premature.
Praga-Północ: Major Developments and a Growing Residential Offer
Praga-Północ was one of Warsaw’s largest monitored residential submarkets in early November.
According to Mieszkaniometr, the district had 1,493 apartments available across 25 developments.
The median asking price stood at PLN 17,900 per square metre, slightly above the citywide median.
The district’s available inventory was strongly influenced by major projects, including the development associated with Mennica Polska on Jagiellońska Street.
With 675 apartments listed as available, this was one of the largest individual entries in the Warsaw database.
Its median asking price matched the district-level median of PLN 17,900 per square metre.
Home Factory represented another significant development, with approximately 300 apartments available and a median asking price of PLN 16,200 per square metre.
The difference between these two project medians was PLN 1,700 per square metre.
For a hypothetical 50-square-metre apartment, that would correspond to a price difference of PLN 85,000.
This calculation is illustrative rather than a comparison of identical apartments.
Nevertheless, it demonstrates the range of price positioning within Praga-Północ.
The district combines established urban neighbourhoods with major residential redevelopment opportunities.
Its market appeal cannot be evaluated solely through the district median. Individual projects differ in their surroundings, transport connections, architectural characteristics and apartment specifications.
For developers, the size of the competing inventory makes project differentiation particularly important.
Mokotów: One of Warsaw’s Most Diverse Residential Markets
Mokotów remains one of the capital’s principal residential development locations.
At the beginning of November, 1,399 apartments were listed as available across 41 monitored developments.
The district’s median asking price was PLN 18,250 per square metre, approximately 5.8% above the Warsaw median.
However, Mokotów contains developments operating at substantially different price levels.
In the late-October project snapshot, Rytm Mokotowa recorded 305 available apartments, with a median asking price of PLN 15,400 per square metre.
Archicom Perth on Wołoska Street had 236 apartments available, with a median asking price of PLN 22,329 per square metre.
A Dom Development project on Antoniewska Street recorded 200 apartments, with a median of PLN 16,050 per square metre.
Another Dom Development project on Bokserska Street had 186 apartments available, with a median asking price of PLN 17,275 per square metre.
Aura Mokotów I recorded 184 apartments, with a median of PLN 16,343 per square metre.
The difference between the median asking prices of Rytm Mokotowa and Archicom Perth exceeded PLN 6,900 per square metre.
This illustrates the limitations of using a single district-level indicator for investment comparisons.
Mokotów includes established residential neighbourhoods, major employment locations and areas undergoing continued redevelopment.
As a result, different projects may target buyers with substantially different budgets and preferences.
A meaningful competitive analysis requires comparison at the level of specific locations, apartment sizes, specifications and construction schedules.
Wola: A High-Value Residential Market
Wola stands out as one of Warsaw’s most expensive primary residential submarkets.
On 7 November, the district contained 1,395 apartments across 20 monitored developments.
The median asking price reached PLN 37,500 per square metre, more than twice the citywide median.
The scale of this difference reflects the composition of the monitored residential offer, which includes several high-value projects.
Among them was the development associated with Recap SPV 8 on Grzybowska Street.
The project recorded 396 available apartments, with a median asking price of PLN 38,600 per square metre.
NOHO Warszawa on Karolkowa Street had 277 apartments available, with a median of PLN 50,091 per square metre.
Other projects in the late-October dataset included developments associated with Asbud on Prosta Street and Salerus on Karolkowa Street.
The Asbud project recorded 138 apartments, with a median asking price of PLN 31,024 per square metre.
The Salerus development had 95 apartments, with a median of PLN 28,623 per square metre.
These figures show the strong representation of higher-priced residential projects in the monitored Wola inventory.
They should not, however, be interpreted as evidence that all apartments in the district are priced at this level.
The median reflects the apartments currently included in the database and may be significantly influenced by the concentration of premium developments.
For investors and buyers, this makes detailed project-level analysis particularly important.
In high-value residential schemes, differences in specification, location within the building, views, apartment size and additional amenities can have a substantial impact on the total purchase price.
Ursus: A Large Residential Market with Distinct Price Segments
Ursus remains one of Warsaw’s important locations for large-scale residential development.
At the beginning of November, the district had 1,063 apartments listed as available across 16 monitored developments.
The median asking price was PLN 16,813 per square metre, slightly below the Warsaw median.
The district’s offer includes developments serving different price segments.
UDI TAU on Herbu Oksza Street recorded 253 apartments available, with a median asking price of PLN 16,400 per square metre.
A Marvipol development on Aleje Jerozolimskie had 358 apartments available, with a median of PLN 27,960 per square metre.
In the late-October dataset, Ursus Equilis, associated with the Posag 7 Panien and Gierdziejewskiego area, recorded 283 available apartments at a median asking price of PLN 14,722 per square metre.
The price differences between these developments are substantial.
They demonstrate that the district’s residential market cannot be described as a single uniform segment.
The overall purchase budget, apartment configuration and development specification remain essential when evaluating individual offers.
Praga-Południe: Prices Above the Citywide Median
Praga-Południe had 978 apartments available across 31 monitored developments at the beginning of November.
Its median asking price reached PLN 19,904 per square metre, approximately 15.4% above the Warsaw median.
The district includes projects across a range of locations and price categories.
In the late-October snapshot, Kanwa had 193 apartments available, with a median asking price of PLN 25,000 per square metre.
UNI 3 on Omulewska Street recorded 174 apartments, with a median of PLN 20,700 per square metre.
A development associated with Weisenburger on Żupnicza Street had 115 apartments available, with a median asking price of PLN 18,218 per square metre.
These projects illustrate how different residential developments within Praga-Południe are positioned at different price levels.
The district’s median provides a useful general reference, but the competitive environment must be assessed at project level.
Wawer and Targówek: Different Supply Structures
Wawer had 794 apartments available across 77 monitored developments.
Its median asking price stood at PLN 13,719 per square metre, approximately 20.5% below the Warsaw median.
The relatively large number of developments compared with available apartments indicates a different supply structure from districts dominated by a small number of large schemes.
Targówek, by contrast, had 785 apartments available across 29 monitored developments, with a median asking price of PLN 15,921 per square metre.
One of its largest projects was HI Poborzańska III in the Warszawski Świt area.
The development recorded 386 available apartments, with a median asking price of PLN 16,281 per square metre.
The project therefore represented a substantial share of Targówek’s monitored available inventory.
These two districts demonstrate that similar overall apartment counts can conceal very different development structures.
In one location, inventory may be distributed across numerous smaller projects. In another, a substantial proportion may be concentrated within a few large schemes.
This distinction matters when assessing competitive conditions and the potential impact of new project launches.
Bemowo, Ursynów and Wilanów: Three Different Price Profiles
Bemowo had 596 apartments available across 16 monitored developments on 7 November.
The district’s median asking price stood at PLN 18,000 per square metre.
The late-October project snapshot included Modern City, with 229 apartments and a median asking price of PLN 17,100 per square metre.
Metro Life Apartamenty recorded 191 apartments, with a median of PLN 17,550 per square metre.
Osiedle Kameralne had 137 apartments available, with a median asking price of PLN 17,700 per square metre.
These developments occupied a relatively similar price range.
Ursynów presented a different picture.
The district contained 526 available apartments across 15 developments, with a median asking price of PLN 26,084 per square metre.
In the late-October snapshot, CU-Cynamonowa Ursynów recorded 168 apartments at a median asking price of PLN 26,880 per square metre.
Another development associated with GH Development on Indiry Gandhi Street had 155 apartments, with a median of PLN 26,300 per square metre.
A project on Komisji Edukacji Narodowej Avenue recorded 141 apartments, with a median asking price of PLN 26,929 per square metre.
Wilanów had 395 apartments available across 35 developments, with a median asking price of PLN 18,070 per square metre.
The differences between these districts demonstrate the importance of analysing the composition of the monitored offer rather than relying on assumptions about district prestige or location alone.
Śródmieście: Limited Supply and High Asking Prices
Śródmieście had one of the smallest monitored inventories among Warsaw’s principal residential districts.
On 7 November, 261 apartments were available across 15 developments.
The median asking price stood at PLN 34,408 per square metre, almost twice the Warsaw median.
The district’s supply is relatively limited compared with Białołęka, Mokotów or Wola.
However, the price structure reflects the characteristics of the projects currently being marketed.
Examples of residential developments in central Warsaw include Apartamenty Grzybowska 11, Apartamenty Jana Pawła 34, Flare Apartamenty Grzybowska and Konwiktorska Residence.
These projects illustrate the variety of central residential products, from compact apartments to larger high-value units.
For buyers, the principal considerations include the precise location, building specification, apartment layout, access to transport and the total acquisition cost.
For developers, central projects operate in a market where the availability of suitable sites and the characteristics of the surrounding urban environment can strongly influence product positioning.
The district-level median should not be used as a substitute for evaluating individual apartments.
The Largest Developers: Dom Development, Develia and Other Major Groups
An additional perspective on Warsaw’s primary residential market is provided by the developer-level data published by Metra24.
In its 8 November 2026 snapshot, Metra24 monitored 12,072 apartments across 202 developments.
Within that dataset, Dom Development had the largest available inventory among the listed developers, with 1,591 apartments across 14 projects.
The median asking price for its monitored offer was PLN 16,800 per square metre.
Develia followed with 984 apartments across 13 developments and a median asking price of PLN 16,917 per square metre.
Marvipol had 622 apartments across seven projects, with a median of PLN 24,333 per square metre.
Victoria Dom recorded 620 apartments across 30 developments, with a median asking price of PLN 15,286 per square metre.
Other significant developers in the Metra24 dataset included Home Invest, Archicom, Napollo, Aurec Home and GH Development.
The figures demonstrate the diversity of developer portfolios operating in Warsaw.
Some companies maintain large inventories across numerous developments, while others concentrate their offer in fewer projects or higher-priced segments.
Importantly, the Metra24 dataset covers a narrower range of projects than Mieszkaniometr.
The two inventories should therefore not be added together or treated as directly equivalent measures of the total Warsaw market.
Metra24 is useful as a supplementary reference for understanding developer portfolios and apartment characteristics, while the broader Mieszkaniometr snapshot is used as the principal reference for citywide supply.
Apartment Sizes and Purchase Budgets
The structure of the available apartment inventory is another important feature of Warsaw’s primary residential market.
Metra24 provides a breakdown by the number of rooms.
In its 8 November snapshot, two-room apartments represented the largest category, with 5,317 units available.
Their median floor area was 41 square metres, and the median total asking price was approximately PLN 733,000.
Three-room apartments formed the second-largest category, with 3,907 units available.
Their median floor area was 60 square metres, and the median total asking price was approximately PLN 953,000.
One-room apartments accounted for 1,284 units.
Their median floor area was 32 square metres, while the median total asking price was approximately PLN 813,000.
The relatively high median price per square metre for one-room apartments reflects the composition of the monitored offer and the higher unit prices often associated with smaller apartments in certain locations.
Four-room apartments accounted for 1,358 units, with a median floor area of approximately 81 square metres and a median total asking price of PLN 1.26 million.
These figures demonstrate why the price per square metre should not be the only metric used to assess residential affordability.
The total acquisition cost is particularly important when comparing apartments intended for different household sizes.
A lower price per square metre does not necessarily translate into a lower total purchase price, particularly where the apartment is significantly larger.
October 2026: Asking Prices Show Limited Underlying Movement
The October 2026 Mieszkaniometr report provides an important distinction between changes in the composition of available inventory and actual changes in developers’ asking prices.
At the end of October, Warsaw had 17,642 apartments listed as available in the monitored dataset.
The median asking price stood at PLN 17,200 per square metre.
This represented a 1.9% increase in the overall median compared with September.
However, the average price change for the same apartments present in the database at the end of both months was only +0.1%.
The difference is significant.
Changes in the citywide median can result from new developments entering the database, apartments leaving the monitored offer or changes in the geographical and price composition of available inventory.
They do not necessarily indicate equivalent changes in developers’ published prices for existing apartments.
The matched-apartment index provides a more direct indication of price-list adjustments.
In October, price reductions affected 2.1% of the monitored Warsaw inventory.
This does not suggest widespread discounting across the market.
At the same time, it does not establish that individual developments were unaffected by price changes.
Commercial strategies can differ substantially between projects and apartment categories.
The available data supports a conclusion of limited underlying price movement in October, rather than a broad-based increase matching the change in the citywide median.
Why Warsaw’s Median Price Cannot Describe the Entire Market
The most striking characteristic of Warsaw’s primary residential market is the range of prices between districts and individual projects.
In Białołęka, the district median stood at PLN 13,882 per square metre.
In Wawer, it was PLN 13,719.
By comparison, Mokotów recorded PLN 18,250, Praga-Południe PLN 19,904, and Ursynów PLN 26,084.
In Śródmieście, the median reached PLN 34,408, while Wola recorded PLN 37,500.
The difference between the district medians of Wola and Białołęka exceeded PLN 23,600 per square metre.
For a hypothetical 50-square-metre apartment, the arithmetic difference would exceed PLN 1.18 million.
Such a comparison is not a valuation of equivalent apartments.
It illustrates the magnitude of market segmentation and the importance of examining individual properties rather than drawing conclusions from citywide indicators.
Even within the same district, project-level differences can be substantial.
For this reason, professional residential market analysis should combine citywide data with district-level and project-level evidence.
What Does the Current Supply Mean for 2027?
Warsaw’s primary residential market enters the final part of 2026 with substantial available inventory and pronounced differences between individual districts.
For developers, the key challenge is not simply the overall volume of apartments on the market.
It is the relationship between the available apartment mix, project positioning, asking prices and actual buyer demand in each local submarket.
In districts with large residential inventories, competing projects may offer similar apartment sizes and target similar buyers.
In higher-priced locations, the competitive environment may depend more heavily on specification, micro-location and the characteristics of individual apartments.
The timing of new development phases is also relevant.
Introducing additional apartments into an area with a substantial existing offer can intensify competition, particularly where the projects occupy similar price segments.
However, it would be inappropriate to conclude that Warsaw is experiencing general oversupply solely because more than 16,600 apartments are listed as available.
Such a conclusion would require verified sales absorption figures, the volume of new launches and a consistent measurement of the available inventory over time.
The same applies to predictions of price reductions.
October’s matched-apartment price data shows limited movement, but it does not establish the direction of future prices.
The most defensible conclusion is that Warsaw remains a highly segmented market in which competitive conditions vary considerably between districts and developments.
Warsaw: A Market Defined by Scale, Segmentation and Project-Level Competition
Warsaw’s primary residential market is characterised by substantial available supply, a wide range of residential products and significant price differences.
At the beginning of November 2026, the monitored market comprised 515 developments and 16,618 available apartments, with a median asking price of PLN 17,250 per square metre.
Białołęka was the largest district market by available apartment inventory, followed by Praga-Północ, Mokotów and Wola.
The largest individual projects included developments on Jagiellońska, Grzybowska and Warszawski Świt, alongside major residential schemes in Ursus and other districts.
At the same time, the capital’s residential offer extends across very different price categories.
Large developments in outer districts operate at median asking prices around PLN 12,000–16,000 per square metre, while selected projects in central Wola exceed PLN 38,000 or even PLN 50,000 per square metre.
The October data indicates limited underlying changes in asking prices for apartments already on the market.
For developers, competitive positioning, apartment mix and the timing of new phases remain central to commercial strategy. For purchasers and investors, the most relevant assessment is the comparison of individual developments and apartments within clearly defined local markets.
Warsaw cannot be understood through a single average or median price.
Its primary residential market consists of multiple submarkets, each with its own supply structure, pricing characteristics and competitive environment.
---
Methodology and Sources
This analysis covers exclusively Warsaw’s primary residential market.
Citywide and district-level figures are based on the Mieszkaniometr snapshot dated 7 November 2026.
The principal project-level figures are drawn from the 7 November snapshot, with additional explicitly identified project examples taken from the late-October dataset.
The October pricing analysis is based on Mieszkaniometr’s monthly report for October 2026.
Supplementary information on developer portfolios, apartment sizes and purchase budgets comes from Metra24, using its 8 November 2026 snapshot.
The two databases cover different sets of residential developments and should not be aggregated.
Available apartments refer to units listed in the monitored offer and should not be interpreted as the total number of unsold apartments across entire developments.
The article does not provide project-level sales volumes, sales ratios or sales absorption rankings where sufficiently verified and comparable information is unavailable.
Sources: Mieszkaniometr, Metra24, publicly available developers’ price lists, and Poland’s public data portal.